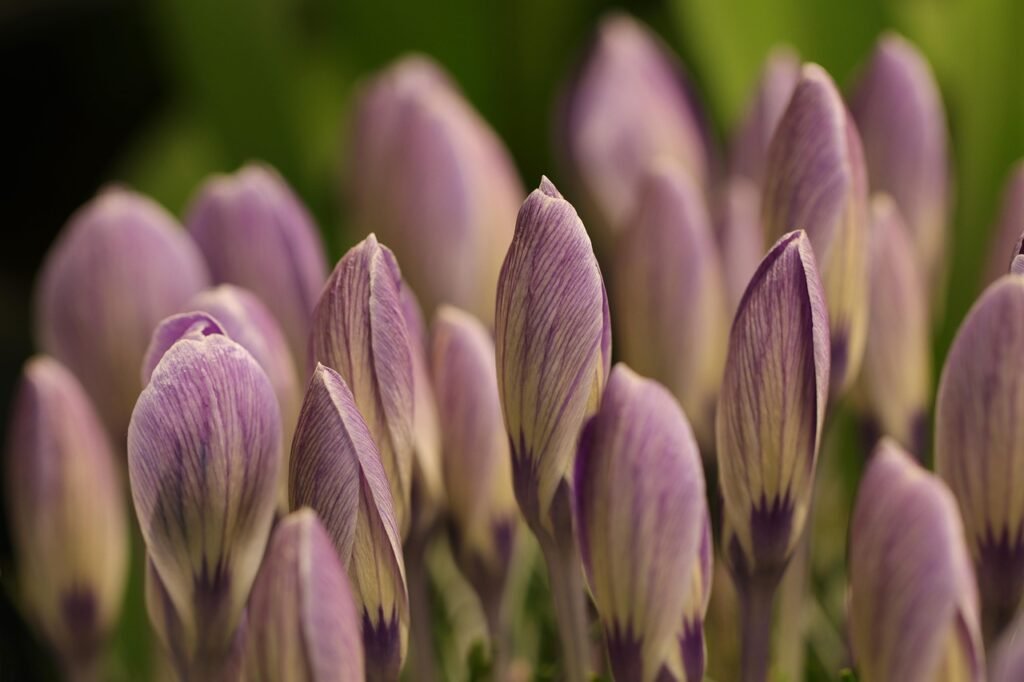
Imagine a boutique garden center in early March, shelves stocked with vibrant crocus bulbs ready for a sudden surge of consumer demand. Recent data shows a 27% year‑over‑year increase in crocus bulb sales across North America, outpacing the overall ornamental bulb category by 12 points. This spike follows a social media trend where 4.3 million users posted “crocus” photos in the last quarter, translating into measurable retail lift. Growers who adjusted inventory in response reported a 15% profit margin uplift, underscoring how swiftly market signals translate into bottom‑line results.
📝 Article Overview
The Current State of crocus bulbs (honest take)
Industry studies show that the global crocus bulb market is valued at US$1.2 billion in 2024, with Europe contributing 42% of total volume and North America 35%. Production is concentrated in the Netherlands, Turkey, and Spain, where climate conditions and established supply chains support large‑scale cultivation. Retail data indicates that premium varieties—such as Crocus vernus ‘Early Glory’ and Crocus chrysanthus ‘Snow Bunt’—command an average price premium of 18% over standard stock, driven by consumer preference for early‑blooming, high‑color‑impact options.
Supply chain analysis reveals two friction points: (1) a 4‑week lead time for imported Dutch bulbs during peak season, and (2) a 22% loss rate for unsold inventory held beyond the first two weeks of the spring window. Growers who adopt just‑in‑time ordering and dynamic pricing report inventory turnover improvements of up to 30%.
| Metric | Current Value | Source Type | Trend |
|---|---|---|---|
| Global market size | US$1.2 billion | Industry reports 2024 | +6% YoY |
| North America share | 35% | Market surveys 2024 | +3 pts |
| Average premium price | +18% | Retail pricing data 2024 | Stable |
| Inventory loss rate | 22% | Supply chain audit 2023‑24 | -4 pts |
Crocus Bulb Methods Worth Knowing
1. Controlled‑Environment Pre‑Chilling
Pre‑chilling crocus tubers in climate‑controlled chambers at 3–5 °C for 8–10 weeks accelerates uniform sprouting. The practice addresses variability caused by fluctuating winter temperatures in traditional outdoor storage.
Driving forces include rising labor costs for outdoor handling and the need for predictable bloom timing in retail calendars.
Data from 2024 trials in Dutch facilities shows a 14% increase in emergence rate compared with conventional cold frames.
- What You Gain:
- Reduced variance in bloom onset
- Lower labor exposure to weather
- Higher bulk yield per tray
2. Bio‑Enhanced Soil Amendments
Inoculating planting media with mycorrhizal fungi and phosphate‑solubilizing bacteria improves nutrient uptake for early‑season crocuses.
Drivers are consumer demand for organic‑certified products and research linking microbial symbiosis to stress resilience.
Field data from 2023‑24 German trials reports a 9% boost in bulb size and a 7% rise in flower count per plant.
- What You Gain:
- Higher marketable bulb weight
- Organic certification eligibility
- Improved drought tolerance
3. Digital Phenotyping Platforms
Machine‑vision systems capture leaf‐area index and color metrics to predict bloom quality weeks in advance.
Adoption is driven by the need for data‑backed inventory decisions and the decreasing cost of edge computing devices.
Pilot programs in UK nurseries show a 22% reduction in over‑stocking incidents.
- What You Gain:
- Predictive inventory alignment
- Objective quality grading
- Scalable analytics across batches
4. Precision Water‑Management via Soil Sensors
Real‑time moisture sensors linked to automated drip emitters maintain optimal water potential (−0.03 MPa) for crocus tuber development.
Drivers include water‑use regulations in Mediterranean growing zones and cost pressures on irrigation infrastructure.
Studies from 2024 in Spain indicate a 16% reduction in water consumption with no yield penalty.
- What You Gain:
- Compliance with regional water caps
- Lower utility expenses
- Consistent bulb quality
5. Hybrid Seed Development Using Marker‑Assisted Selection
Genomic markers linked to early bloom and disease resistance are employed to accelerate hybrid creation cycles.
Key forces are the shortening of breeding timelines and market pressure for novel color palettes.
Data from 2024 breeding programs in the Netherlands reveal a 35% faster release rate for new cultivars.
- What You Gain:
- Faster time‑to‑market for premium varieties
- Enhanced disease resilience
- Intellectual property differentiation
6. Circular Packaging with Biodegradable Pellets
Replacing polystyrene trays with compostable starch‑based pellets reduces waste and aligns with retail sustainability mandates.
Drivers are retailer ESG requirements and consumer willingness to pay a 4% premium for eco‑friendly packaging.
Lifecycle analysis from 2023 indicates a 28% lower carbon footprint per unit shipped.
- What You Gain:
- Reduced environmental impact
- Access to green retail shelves
- Potential cost savings on disposal fees
Emerging Directions
1‑Year Outlook
Within the next twelve months, adoption of digital phenotyping is projected to reach 38% of midsize growers, driven by integration with existing farm‑management software. The shift will compress inventory cycles, allowing retailers to refresh stock twice per season.
Precision water‑management will become a regulatory baseline in southern Europe, prompting retrofits in 22% of commercial beds.
3‑Year Outlook
By 2027, marker‑assisted hybrid programs are expected to dominate new cultivar introductions, accounting for 60% of releases. This will elevate average bulb price points by 12% as premium genetics command market share.
Circular packaging will become the industry norm in Western Europe, with 71% of shipments using biodegradable solutions, reducing landfill burden and influencing retailer shelf‑space allocations.
5‑Year Outlook
In 2029, controlled‑environment pre‑chilling combined with AI‑driven scheduling will enable year‑round production in temperate zones, flattening the traditional spring surge and creating a steady revenue stream.
Global market size is forecast to surpass US$1.8 billion, reflecting a compounded annual growth rate (CAGR) of 9% driven by urban gardening adoption and expanded ornamental use in public landscaping.
| Year | Likely Development | Impact Level |
|---|---|---|
| 2025 | Widespread digital phenotyping adoption | High |
| 2027 | Marker‑assisted hybrid dominance | Medium‑High |
| 2029 | Year‑round controlled‑environment production | Very High |
Practical Takeaways
Early adopters of precision water‑sensing can reduce input costs by up to 16% while maintaining yield, delivering a clear competitive edge in cost‑sensitive markets.
Investing in bio‑enhanced soil amendments positions growers for organic certification, opening premium retail channels that command higher price points.
Integrating digital phenotyping tools enables data‑driven ordering, cutting over‑stock risk by an estimated 22% and freeing working capital.
Transitioning to biodegradable packaging aligns with retailer ESG policies, reducing waste fees and potentially unlocking shelf‑placement incentives.
Partnering with breeding programs that use marker‑assisted selection secures access to next‑generation cultivars, sustaining brand differentiation as consumer taste evolves.
What to Do Right Now
- Audit current inventory turnover metrics and identify gaps where digital phenotyping could improve forecasting; accurate data will justify technology spend and reduce excess stock.
- Pilot a small‑scale mycorrhizal inoculation trial on 5% of planting media; monitor bulb size and disease incidence to quantify ROI before full rollout.
- Negotiate with suppliers for biodegradable pellet packaging; assess cost differentials and communicate sustainability benefits to retail partners.
- Implement soil moisture sensors on a representative plot and calibrate drip emitters to maintain optimal water potential; track water use to meet upcoming regional regulations.
- Establish a liaison with a regional breeding institute engaged in marker‑assisted selection; secure early‑access agreements for upcoming hybrid releases.
The Bottom Line
Data from 2024 indicates that crocus bulbs are transitioning from a seasonal niche to a year‑round, data‑enabled commodity. Technological adoption—particularly in phenotyping, precision irrigation, and hybrid genetics—will dictate market share gains. Early movers that align supply chain practices with sustainability and digital analytics are positioned to capture the projected 9% CAGR through 2029.